How to Evaluate ROI on Caribbean Property
Evaluating ROI on Caribbean property requires looking beyond the advertised purchase price or rental yield. A proper calculation should include the total acquisition cost, rental income, vacancy, management fees, maintenance, insurance, taxes, HOA or resort charges, financing costs and eventual selling expenses. The first useful measure is gross rental yield, but investors should focus more on net operating income and cash-on-cash return. Current 2026 data shows that Caribbean markets vary considerably. For example, Global Property Guide reports an average gross rental yield of 8.53% in the Dominican Republic, with Santo Domingo at 9.09% and Punta Cana-Bávaro at 7.98%. These are gross figures before taxes, maintenance, vacancies and other costs.
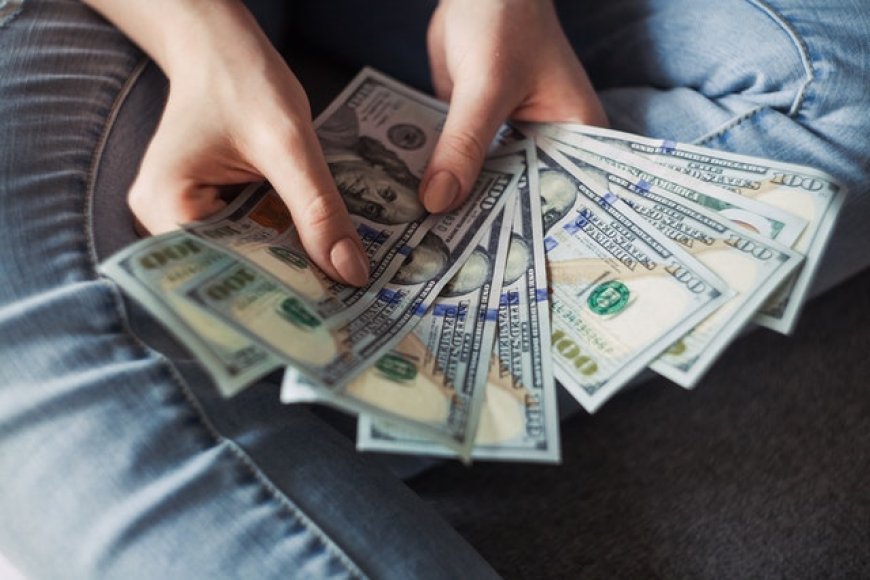
Investing in Caribbean property can look straightforward from a distance. A beachfront apartment, a villa near a resort, or a condominium in a popular tourist destination can appear to offer two potential benefits at the same time: rental income and long-term property appreciation. But calculating the real return on a Caribbean property requires much more than comparing the purchase price with the advertised monthly rent. Investors have to consider occupancy, seasonality, management fees, insurance, taxes, maintenance, financing, currency, legal requirements for foreign buyers, hurricane and climate risks, property management, and the eventual cost of selling. The Caribbean is not one property market. It is a collection of different markets, currencies, legal systems, tourism patterns, tax structures, and real estate conditions. Therefore, an investment that produces attractive rental income in one island or city may have a very different financial profile in another.

Tourism is one of the main factors supporting Caribbean rental demand. According to the Caribbean Tourism Organization, international tourist arrivals to Caribbean destinations reached an estimated 35 million in 2025, an increase of 2.5% from 2024, while stay-over visitors exceeded the 2019 benchmark by 9.6%. The organization estimated that international arrivals were increasing by about 3.9% in early 2026 and projected annual growth in the range of 3% to 4% for 2026. This creates an important foundation for property investors because tourism can generate demand for hotels, vacation rentals, villas, apartments, and other accommodation. However, rising visitor numbers do not automatically mean that every property will produce a strong return. The investor still has to determine whether the particular property, location, price, operating model, and costs make financial sense.
Start With the Definition of ROI
Before calculating anything, it is important to understand what “ROI” actually means. Return on investment can refer to several different measurements. For a Caribbean property, the simplest calculation is rental yield, but rental yield alone does not provide the complete picture.
Gross rental yield is calculated by taking the annual rental income and dividing it by the purchase price of the property. For example, if an apartment costs $300,000 and generates $24,000 in annual rent, the gross rental yield is 8%.
The calculation is:
Gross rental yield = Annual rental income ÷ Property purchase price × 100
This number is useful for comparing properties, but it leaves out many expenses. If the property costs $24,000 a year to operate, the investor cannot treat the entire $24,000 in rent as profit.
A more useful calculation is net rental yield. This takes operating expenses into account.
Net rental yield = Annual net rental income ÷ Total investment × 100
The phrase “total investment” is important. The investor should not automatically use only the advertised property price. The real investment may include legal fees, government charges, transfer taxes, furnishing, renovation, insurance, financing costs, furniture replacement, closing expenses, and other acquisition costs.
This is why two properties with the same purchase price and advertised rental income can have very different actual returns.
Look at the Total Purchase Cost
The first step in evaluating ROI is determining exactly how much capital will be required to acquire the property.
Suppose a Caribbean apartment is advertised at $350,000. The investor should not immediately calculate the return using $350,000. Instead, create a complete acquisition budget. Depending on the jurisdiction and transaction, the buyer may face legal fees, property transfer taxes, registration charges, real estate commissions, government permits or licences for foreign purchasers, inspection costs, financing fees, furnishing costs, and renovation expenses.
Foreign ownership rules can also affect the calculation. InvestCARICOM notes that foreigners can invest in real estate across CARICOM jurisdictions, but the terms are not necessarily the same as those for nationals. Some jurisdictions require non-national buyers to obtain licences or permits before acquiring land.
This means that an investor should investigate the ownership process before assuming that the advertised purchase price represents the complete cost of entering the market.
The same principle applies when a property is marketed as part of a citizenship-by-investment programme. Such properties can have a different investment structure, resale restriction, and buyer pool than ordinary residential property.
For example, Antigua and Barbuda's official Citizenship by Investment Programme currently lists approved real estate investment at a minimum value of US$300,000, with additional government processing and due-diligence fees. Property purchased under the programme generally cannot be resold until five years have passed, unless the investor purchases another officially approved property under the programme. An investor evaluating such a property must therefore calculate both the financial return and the effect of the holding requirement on liquidity.
Calculate Rental Income Realistically
The next step is estimating how much money the property can actually generate.
For a long-term rental, the calculation may be relatively simple. If an apartment rents for $2,000 per month and remains occupied throughout the year, the theoretical annual rent is $24,000.
But assuming 100% occupancy is usually unrealistic.
For a vacation rental, the calculation becomes more complicated because nightly rates and occupancy vary throughout the year. A property might achieve strong rates during Christmas, New Year, winter travel periods, festivals, or other peak periods while producing much lower income during the shoulder and low seasons.
A useful starting formula is:
Annual rental revenue = Average nightly rate × Occupied nights
Suppose an investor expects an average realized rate of $250 per night and 200 occupied nights per year. Gross rental revenue would be $50,000.
But the important phrase is “realized rate.” An advertised rate of $300 is not necessarily the amount the owner receives. Discounts, promotions, platform fees, cancellations, management charges, and other deductions can reduce the amount actually collected.
Investors should therefore request actual historical performance from the property manager or seller where available rather than relying only on projected figures.
Do Not Confuse Gross Yield with Net Yield
Gross rental yield can make a property look more attractive than it really is.
Global Property Guide's September 2026 data, for example, reports an average gross rental yield of 8.53% for the Dominican Republic in Q1 2026. It reports an average of 9.09% in Santo Domingo and 7.98% in Punta Cana/Bavaro. The publication also explicitly notes that these are gross yields and that net yields are typically lower after taxes, maintenance, vacancies, management and other expenses.
This distinction is critical.
Imagine a property costing $250,000 that produces $20,000 in annual gross rent. The gross yield is 8%. If operating expenses total $6,000, the net operating income before financing and taxes becomes $14,000. The net yield on the purchase price is then 5.6%.
If the investor also spent $20,000 on closing, furnishing and improvements, the effective return on the total capital invested would be lower.
That is why investors should calculate at least three numbers: gross rental yield, net operating yield, and total return.
Include Property Management Costs
Property management can have a significant effect on Caribbean rental ROI, especially when the owner lives overseas.
A local manager may handle guest communication, check-ins, cleaning coordination, maintenance, marketing, booking management, emergency calls, and inspections. These services can save the owner considerable time, but they come at a cost.
Short-term rental management fees may be structured as a percentage of rental revenue, while long-term management may involve a different fee arrangement. There may also be separate charges for cleaning, maintenance coordination, linen services, marketing, repairs, or guest services.
An investor should ask for the complete fee schedule before purchasing.
It is also important to determine whether the quoted management percentage applies to gross booking revenue or net revenue after platform fees. A 20% management fee applied to gross revenue is not financially equivalent to 20% of a smaller net figure.
Account for Vacancy
Vacancy is one of the most important variables in rental property investment.
For a long-term rental, the property may sit empty between tenants. For a vacation rental, the issue is more complicated because occupancy changes by season.
Investors should avoid using the best month as the basis for annual ROI. Instead, look at the full calendar.
For example, assume a property can charge $300 per night during a peak period, $220 during shoulder season, and $150 during low season. The investor should estimate occupancy separately for each period rather than simply multiplying the peak rate by 365 days.
This produces a much more realistic model.
It is also useful to create three scenarios: conservative, base, and strong performance. The conservative scenario assumes lower occupancy and higher expenses. The base scenario reflects what the investor considers a reasonable expectation based on comparable properties. The strong scenario assumes favourable performance.
If the investment only works under the strongest scenario, that is important information.
Study the Local Rental Market
A Caribbean property should be compared with similar properties in the same market, not with properties somewhere else on the island or in another Caribbean country.
Look at properties with similar size, location, views, amenities, age, condition, parking, swimming pool access, beach access, and management arrangements.
For vacation rentals, compare actual nightly rates and occupancy where data is available. For long-term rentals, examine asking rents as well as the length of time properties remain vacant.
Global Property Guide's Caribbean rental-yield database is one example of a source that tracks gross rental yields across Caribbean cities using property prices and rental rates from local listings. Its September 2026 update notes that the dataset is updated periodically using median property prices and rental rates.
However, investors should treat listing data as an indicator rather than proof of actual transaction performance. Asking prices are not necessarily final selling prices, and asking rents are not necessarily achieved rents.
Understand Tourism Demand
Tourism is particularly important for investors considering short-term rentals.
The Caribbean Tourism Organization reported approximately 35 million international tourist arrivals in 2025. That broad regional number is useful, but it should not be used as a substitute for destination-level research.
The important question is: Who is visiting this particular location, when are they visiting, and where are they staying?
A destination that receives large numbers of cruise passengers may have strong visitor traffic but not necessarily the same demand for overnight vacation rentals as a destination dominated by stay-over visitors.
Likewise, an island with a large winter market may experience very different occupancy patterns from one that attracts visitors throughout the year.
Investors should examine airport arrivals, hotel occupancy, tourism statistics, visitor source markets, average length of stay, cruise traffic, new hotel developments, airline routes, and major events.
The more detailed the local tourism picture, the more reliable the rental-income forecast becomes.
Consider the Short-Term Rental Rules
Short-term rental regulations have become increasingly important throughout the Caribbean.
A property that looks profitable as a vacation rental may not be permitted to operate in that way without registration, licensing, taxes, zoning approval, strata or condominium approval, or other requirements.
In May 2026, the Caribbean Hotel and Tourism Association released a regional framework for short-term rentals, noting that STRs have become a permanent part of Caribbean tourism. The organization cited one major Caribbean destination where short-term-rental visitor nights increased 118% between 2019 and 2025 and represented 39% of visitor accommodation in the first quarter of 2026. The broader trend makes regulatory research especially important.
Before purchasing, confirm whether short-term rentals are legal at the national, municipal, development, and building levels. A condominium association may impose restrictions even if national law allows vacation rentals.
The investor should also determine whether tourist accommodation taxes, VAT, sales taxes, income taxes, or other charges apply.
Include Insurance in the ROI Calculation
Insurance is a major consideration in Caribbean property investment because the region is exposed to hurricanes, flooding, coastal erosion, storms, and other natural hazards.
The correct question is not simply, “How much does insurance cost?” The investor should ask, “How much does insurance for this specific property actually cost, and what does the policy cover?”
Obtain an insurance quote before completing the purchase whenever possible.
Check hurricane coverage, windstorm deductibles, flood coverage, liability protection, building coverage, contents, business interruption, and exclusions. A low annual premium may not be useful if the deductible is extremely high or major risks are excluded.
InvestCARICOM identifies insurance costs driven by catastrophe exposure as one of the measurable risks in Caribbean real estate, alongside issues such as title quality and market liquidity. Insurance costs can therefore change the ROI calculation significantly.
Do Not Ignore Maintenance
Tropical climates can create maintenance requirements that are different from those in many temperate markets.
Salt air can accelerate corrosion. Humidity can contribute to mould and moisture problems. Heavy rainfall can affect drainage. Air-conditioning systems may operate heavily throughout the year. Swimming pools, landscaping, roofs, plumbing, exterior paint, and appliances can all require regular attention. A property with an attractive purchase price may require substantial maintenance spending.
Investors should establish an annual maintenance reserve rather than assuming that maintenance will be minimal.
For an older property, obtain an independent inspection and pay particular attention to the roof, electrical systems, plumbing, air conditioning, windows, drainage, structural condition, and signs of water intrusion.
Evaluate the Property's Location
Location is more than being “near the beach.”
For a rental property, examine how close the property is to airports, beaches, restaurants, supermarkets, attractions, medical services, entertainment areas, marinas, business districts, and transportation.
Walk ability can be valuable. A property where guests can reach restaurants and shops without renting a car may have a different rental profile from a similar property that requires transportation for everything.
However, being directly on the coast can also increase exposure to storms, salt, flooding, and erosion. The ideal location therefore involves balancing rental demand with operating and insurance risks.
Calculate Financing Costs Separately
If the property is financed, the mortgage should not be hidden inside the general ROI calculation. First calculate the property's operating performance without debt. This tells you whether the property itself generates sufficient income. Then calculate the impact of financing.
Suppose a property generates $30,000 in net operating income before mortgage payments. If annual debt service is $20,000, the remaining cash flow is $10,000 before income taxes and other applicable expenses.
The investor should also calculate the debt-service coverage ratio and stress-test the investment against higher interest rates, lower occupancy, or unexpected repairs.
Financing can increase the return on the investor's own cash when an investment performs well, but it also increases financial risk when rental income falls.
Include Currency Risk
Currency is another important consideration for international investors. Some Caribbean markets use the U.S. dollar directly, while others use currencies pegged to the U.S. dollar or operate with independent currencies. InvestCARICOM identifies U.S.-dollar or pegged-currency pricing across much of the region as one factor investors may consider, while also highlighting differences in local legal and market conditions.
An investor whose income and savings are in euros, pounds, Canadian dollars, Indian rupees, or another currency should calculate returns in both the property's operating currency and their home currency.
A property can produce the expected local-currency return while the investor's home-currency return changes because exchange rates move. Currency conversion fees and international banking charges should also be considered.
Calculate Capital Appreciation Carefully
Rental income is only one component of property ROI. The second major component is capital appreciation. If a property purchased for $300,000 is later sold for $360,000, the investor has a nominal $60,000 capital gain before selling expenses, taxes, financing considerations, and inflation.
But investors should not assume that property prices will always rise.
Research recent comparable sales rather than relying on a developer's projected appreciation. Examine how prices have behaved over several years, where possible, and compare similar properties rather than using island-wide averages.
Also consider whether the property is easy to resell. A luxury villa may have a smaller pool of potential buyers than a reasonably priced apartment.
Understand Liquidity
Liquidity is often overlooked in property investment. A listed property may take months to sell, and the eventual sale price may be below the original asking price. Investors should therefore ask who the likely future buyer will be.
Will the next buyer be a local resident, an overseas investor, a retiree, a vacation-home buyer, or someone interested in a citizenship-by-investment programme? The answer can influence the property's resale potential.
InvestCARICOM specifically identifies thin liquidity as one of the risks that investors should consider in Caribbean real estate. This is one reason why investors should avoid evaluating a property solely on its rental yield.
Calculate the Cost of Selling
ROI calculations should include the eventual exit. When the property is sold, the investor may pay a real estate agent commission, legal fees, taxes, government charges, outstanding maintenance or association fees, and other transaction costs.
If the property is purchased for $300,000 and sold for $400,000, the investor does not automatically make $100,000.
The correct calculation starts with the total acquisition cost and subtracts the total selling cost from the sale proceeds. Only then can the actual capital gain be established. For long-term investments, investors should model at least one realistic exit scenario.
Consider Taxation
Taxes can substantially affect Caribbean property ROI. Depending on the jurisdiction and the investor's circumstances, there may be property taxes, rental income taxes, transfer taxes, stamp duties, capital gains taxes, withholding taxes, tourism taxes, VAT, or other charges. There may also be tax obligations in the investor's home country.
Tax rules vary significantly between Caribbean jurisdictions, so an investor should obtain advice from professionals familiar with both the property jurisdiction and the investor's tax residence. The key is to calculate returns after applicable taxes rather than using a pre-tax marketing figure.
Check the Title and Legal Status
A strong rental projection cannot compensate for a legal problem with the property. InvestCARICOM emphasizes that title and land-registration issues can be among the most important factors in Caribbean real estate transactions. Its September 2026 analysis notes that some jurisdictions still use paper-based land registers and that the quality and accessibility of title records can vary.
An independent attorney should conduct proper due diligence. The investor should confirm ownership, boundaries, liens, mortgages, planning permissions, building approvals, easements, access rights, condominium obligations, and any restrictions affecting the property.
If the property is being sold as part of a development, investors should also investigate the developer's track record and the legal status of the development.
Investigate the Developer
New-build developments can offer attractive amenities and payment plans, but the developer's history matters. Look at completed projects rather than relying solely on renderings and promotional material. Check whether previous projects were delivered on schedule, whether promised amenities were completed, and how owners experienced the management process after completion.
Ask who will manage the property after construction. A well-designed property can still perform poorly if the management structure is weak.
For off-plan purchases, investors should understand construction timelines, payment milestones, cancellation provisions, completion guarantees, and what happens if the project is delayed.
Build a Full ROI Spreadsheet
A good Caribbean property analysis should bring all these variables together.
A basic model should include:
Purchase price + acquisition costs + renovation/furnishing = total initial investment.
Then calculate:
Gross rental income – vacancy – management – maintenance – insurance – utilities paid by owner – taxes – association fees – other operating costs = net operating income.
After that, calculate:
Net operating income – financing costs = cash flow before personal income taxes.
Finally, when considering a sale:
Sale price – selling costs – outstanding debt = net sale proceeds.
This allows the investor to calculate both annual cash return and total investment return.
Example of a Caribbean Property ROI Calculation
Consider a hypothetical Caribbean apartment purchased for $300,000.
Suppose acquisition costs and furnishing total another $25,000, bringing the initial investment to $325,000.
Assume the property generates $36,000 in annual gross rental revenue. Now deduct $5,000 for property management, $3,500 for maintenance and utilities, $2,500 for insurance, $2,000 for association fees, and $2,000 for taxes and other operating costs.
That leaves approximately $21,000 in annual net operating income.
The net operating return on the $325,000 invested would be approximately 6.46%.
This is much more informative than saying the property produces $36,000 in annual rent.
If the property also appreciates, the total return can be higher. But appreciation should be treated as a separate assumption rather than guaranteed income.
The investor should then test what happens if annual rental income falls by 15%, insurance increases, maintenance costs rise, or occupancy declines.
Stress-Test the Investment
A property that works only under perfect conditions deserves additional scrutiny. Create a conservative scenario. Reduce occupancy. Lower the average rental rate. Increase insurance. Add unexpected maintenance. Consider a period without tenants. Then see whether the property still produces positive cash flow.
For example, if a property produces $21,000 of net operating income under normal conditions but only $8,000 under a conservative scenario, the investor should understand why.
The objective is not to predict the future perfectly. It is to understand how sensitive the investment is to changes.
Compare Multiple Caribbean Markets
Investors should resist the temptation to compare only advertised purchase prices. A $250,000 property in one destination may produce less rental income than a $350,000 property in another. A cheaper property may also have higher insurance, lower occupancy, weaker resale demand, or greater maintenance requirements.
Compare markets using the same categories: acquisition cost, gross rent, occupancy, operating costs, taxes, insurance, legal restrictions, financing, appreciation history, liquidity, and exit costs. This creates a much clearer picture.
The Caribbean Tourism Organization's regional statistics can provide a broad tourism context, but investors should combine that information with local property data before making a decision.
Look Beyond the Beachfront Premium
Beachfront property often commands a premium, but the additional purchase price does not automatically translate into an equivalent increase in rental income.
For example, a beachfront apartment might cost $500,000 while a property five minutes away costs $350,000. If the beachfront unit generates $40,000 in annual net income and the nearby property generates $32,000, the cheaper property could produce a higher yield despite having lower absolute income.
The correct comparison is therefore between incremental purchase cost and incremental income. Investors should also consider the higher insurance and maintenance exposure that can come with coastal properties.
Consider Personal Use
Many Caribbean property buyers are not purely investors. They may want to use the property themselves for several weeks each year.
That is perfectly reasonable, but personal use has an economic cost.
If a property could generate $300 per night during a period when the owner uses it personally for 20 nights, the potential gross rental revenue sacrificed could be $6,000. This does not mean personal use is a bad idea. It simply needs to be included in the ROI calculation. A useful model can calculate two versions: investment-only performance and performance after personal use.
Consider the Management Model
There are three common approaches: owner-managed, locally managed, or professionally managed.
Owner management can reduce fees but is difficult when the owner lives thousands of kilometres away.
Local management can provide flexibility but requires finding trustworthy people.
Professional management can simplify operations but may reduce net income.
The choice should depend on the investor's location, experience, time availability, and the property's rental strategy.
For an overseas owner, saving management fees may not be worthwhile if the property requires frequent attention.
Watch for Overoptimistic Projections
Property marketing materials often show attractive projected rental income. Investors should ask how those projections were calculated.
Was the occupancy assumption based on comparable properties? Were management fees deducted? Was cleaning included? Were taxes included? Was the projection based on actual historical performance or a forecast?
Ask for evidence.
A projection that assumes 80% occupancy at a premium nightly rate may look impressive, but the investor should test what happens at 55% occupancy and a lower average rate.
The strongest investment analysis is not the one with the highest projected return. It is the one where the assumptions are transparent and can be tested.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0