Caribbean Real Estate Investment: Complete Guide for Foreign Buyers
Caribbean real estate offers foreign buyers opportunities to invest in holiday homes, rental properties, residential developments, commercial buildings, and land. Popular destinations include Barbados, Jamaica, the Bahamas, the Dominican Republic, Antigua and Barbuda, Grenada, and Turks and Caicos. Each destination has its own property laws, foreign ownership requirements, taxes, financing options, and market conditions, so investors should research individual locations before making a decision. Successful property investment requires more than finding an attractive property at a competitive price. Buyers should calculate the full purchase cost, understand local ownership and residency rules, arrange suitable financing, and estimate realistic rental income after expenses. Legal due diligence is essential to verify property titles, land boundaries, construction approvals, and outstanding debts. Investors should also consider hurricane exposure, insurance availability, maintenance costs, property management, and future resale opportunities.
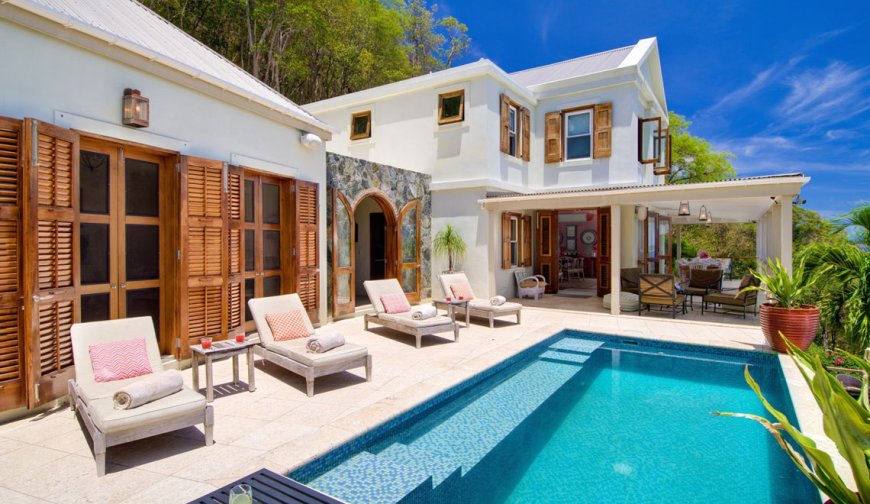
Caribbean real estate attracts international buyers looking for holiday homes, rental income, retirement properties, commercial opportunities, and long-term investments. The region includes independent countries and overseas territories, each with its own property laws, tax rules, currency arrangements, and investment conditions. Some markets offer relatively straightforward ownership for foreign individuals, while others require special licences, government approval, or registration before a purchase can be completed. Tourism supports demand for holiday rentals in selected destinations, but rental income is not guaranteed and property ownership comes with ongoing costs. A successful investment depends on choosing the right location, checking the legal title, understanding taxes, and calculating realistic returns rather than relying only on attractive property listings.

1. Understand the Caribbean Real Estate Market before Investing
The Caribbean is not one single property market. Barbados, Jamaica, the Bahamas, the Dominican Republic, Antigua and Barbuda, Grenada, and Turks and Caicos have different price levels, legal systems, tourism patterns, and ownership requirements. Some locations are known for luxury villas and branded residences, while others offer apartments, family homes, commercial properties, or land for development. Prices can vary significantly within the same island depending on infrastructure, beach access, local employment, transport connections, and demand from overseas buyers. Before investing, compare recent completed sales rather than relying only on asking prices, and examine how long similar properties remain on the market. A location that attracts tourists may still be a weak investment if purchase prices, maintenance costs, and insurance premiums leave little room for profit.
Foreign buyers should also understand who is likely to purchase the property from them in the future. A luxury villa designed for wealthy international buyers may have a smaller resale market than a moderately priced home that appeals to local residents and long-term tenants. Properties near airports, hospitals, schools, business centres, and established tourist areas may serve more than one type of buyer or tenant. However, convenient locations should be assessed alongside flood exposure, construction quality, access roads, water supply, and electricity reliability. Study the local economy and planned infrastructure projects, but do not assume that a proposed hotel, road, or marina will automatically increase property values. A sound market assessment looks at present demand, actual transactions, and the property's likely resale audience.
2. Choose the Right Island and Property Type
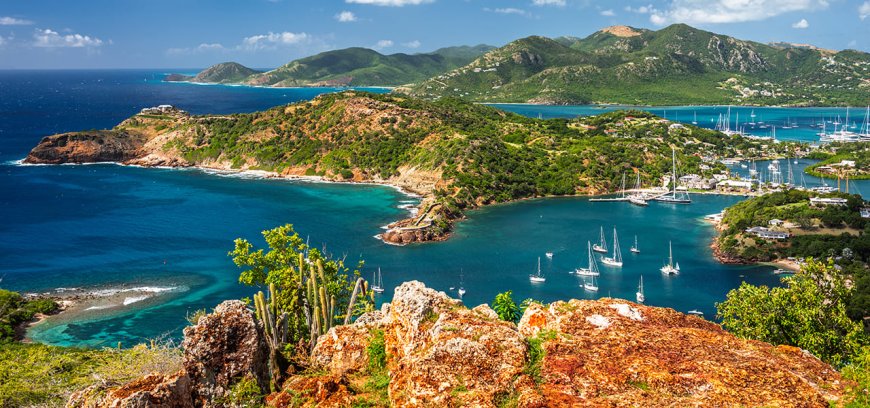
The best destination depends on your investment objective, available budget, risk tolerance, and intended holding period. Barbados appeals to buyers seeking established residential and tourism markets, while Jamaica offers a range of residential, commercial, and holiday-property opportunities. The Bahamas and Turks and Caicos are associated with high-value coastal and resort properties, although entry costs and location-specific expenses can be substantial. The Dominican Republic has a broad market that includes resort apartments, villas, and homes in established urban areas. Antigua and Barbuda, Grenada, and other Eastern Caribbean destinations also attract overseas investors, including buyers interested in second homes and selected citizenship-by-investment property routes. These are broad market characteristics, not guarantees of returns; conditions differ between neighbourhoods and developments.
There are several main property types to consider. A long-term rental home may produce more predictable occupancy than a holiday rental, although tenant demand and payment reliability must be checked. A short-term rental apartment or villa can generate higher nightly rates in peak periods but may experience seasonal vacancies and higher management costs. Commercial properties, such as retail units and office space, depend on local business demand and the financial strength of tenants. Land may offer development potential, but it usually produces no income while the owner pays taxes, security, and maintenance expenses. Resort and branded residences may include management services, but buyers should carefully read the service charges, rental-pool agreements, resale restrictions, and rules governing personal use before committing.
3. Check Foreign Ownership Laws and Residency Requirements
Foreign buyers must verify the ownership rules of the specific country or territory before paying a deposit. In some destinations, foreigners can purchase property without a special landholding licence, while other jurisdictions require a non-citizen to obtain approval or meet additional registration requirements. For example, the Turks and Caicos Islands generally allow foreign individuals to purchase real estate without prior government permission, although rules differ for foreign corporate ownership. In Antigua and Barbuda, non-citizen land purchases may require an Alien Landholding Licence. Barbados has its own exchange-control requirements for non-resident purchasers, including Central Bank permission for real estate transactions. These examples demonstrate why buyers should not assume that a rule applying on one island also applies elsewhere.
Ask an independent local property lawyer to explain whether you can own the property in your personal name, through a company, or under a leasehold arrangement. Confirm the application process, approval fees, expected timeline, minimum landholding conditions, and any restrictions on selling the property later. Company ownership should not be assumed to remove foreign-investment rules, and it can create additional accounting, reporting, and tax obligations. Property ownership also does not automatically grant a right to live, work, or become a permanent resident in the country. Some jurisdictions offer residence pathways linked to qualifying investments, but their eligibility rules and financial thresholds differ from ordinary property-purchase requirements. If residency or citizenship is part of your plan, obtain separate immigration advice and verify the current government programme rules before treating any property as eligible.
4. Calculate the Full Purchase Cost and Taxes
The advertised property price is only one part of the investment. Buyers may also need to pay transfer taxes, stamp duties, legal fees, registration charges, surveys, inspections, licence fees, bank charges, and real estate agent commissions where applicable. The amount and responsibility for each charge depend on local law and the sale agreement. In Barbados, for example, the Central Bank explains that non-residents generally need permission to purchase real estate and that the transaction normally requires the purchase funds to be remitted into Barbados. This is an important practical consideration for overseas buyers arranging payment.
Before making an offer, request a written estimate of all acquisition expenses from an independent local lawyer. Then calculate annual ownership costs, including property tax, building insurance, repairs, security, utilities, condominium fees, and property management. If the property will be rented, include cleaning, advertising, guest services, platform commissions, replacement furniture, and periods when no tenant is paying. Owners who live abroad may also need local accounting services and tax advice in both the property country and their country of residence. Finally, calculate the likely cost of selling, including any applicable transfer charges, capital gains taxes, agent fees, and currency conversion expenses. A property that looks affordable at the purchase stage can become an expensive investment when all these costs are included.
5. Arrange Financing and Plan Your Currency Transfers
Foreign buyers should establish how they will fund the purchase before signing a binding agreement. Some international purchasers use cash or savings held overseas, while others finance the property through a bank in their home country or a lender in the Caribbean destination. Local mortgage availability for non-residents varies, and lenders may request a larger deposit, proof of income, bank statements, tax records, credit history, and evidence of the source of funds. Interest rates, loan terms, eligible currencies, and repayment conditions should be confirmed directly with the lender. Do not assume that a mortgage available to a local resident will also be available to a foreign buyer.
Currency planning is equally important. Several Caribbean economies use the US dollar or maintain a fixed exchange-rate relationship with it, but the region does not share one currency system. If your income is in pounds, euros, Indian rupees, or Canadian dollars, exchange-rate movements can affect the effective purchase price and your future returns. Banks and transfer providers may charge conversion fees, while some jurisdictions require incoming foreign funds to be registered or documented. Keep bank transfer records, purchase agreements, and proof of the source of funds, as these documents may be needed when registering the investment or transferring sale proceeds abroad. Compare the total financing cost, not simply the advertised interest rate, and maintain a cash reserve for repairs, vacancies, and unexpected expenses.
6. Evaluate Rental Income and Calculate Realistic Returns
Rental income is one of the main reasons foreign investors purchase Caribbean property, especially in destinations with established tourism markets. Holiday villas, serviced apartments, and resort residences may attract visitors during peak travel periods, while homes in business centres or residential communities may appeal to long-term tenants. However, rental demand varies by island, neighbourhood, season, property type, and the availability of competing accommodation. Before buying, examine actual occupancy patterns, comparable nightly or monthly rents, local rental regulations, and the services included in property management. A developer's projected rental return is a forecast, not a guaranteed payment.
Calculate gross rental yield by dividing annual rental income by the property's purchase price and multiplying by 100. For example, if a property costs US300, 000andgeneratesUS24, 000 in annual rent before expenses, its gross rental yield is 8%. But suppose operating costs, insurance, management, maintenance, taxes, and vacancy reduce the annual income by US12, 000; theremainingUS12, 000 represents a 4% return on the purchase price before financing costs and any additional taxes. This simplified example shows why gross yield can create an overly positive picture. Build a conservative financial model with high-season and low-season income, realistic occupancy, replacement costs, and a reserve for major repairs. Also calculate how the investment performs if rent falls, insurance rises, or the property remains empty for several months.
7. Complete Legal Due Diligence before Paying the Final Amount
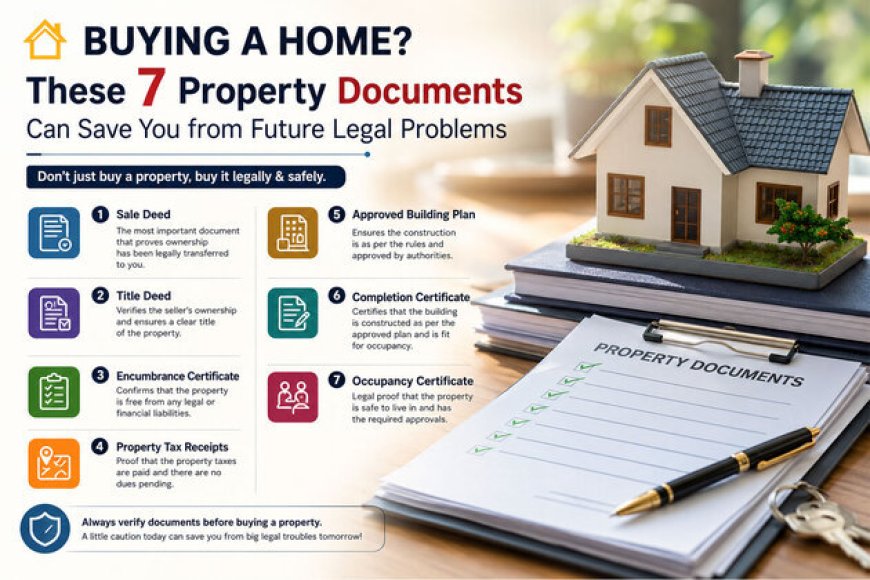
Legal due diligence is essential because the seller's ownership claim, property boundaries, construction approvals, and outstanding obligations must be verified independently. Hire a qualified local attorney who represents your interests rather than relying exclusively on the seller's lawyer, real estate agent, or developer. The attorney should check the registered title or relevant deeds, confirm the seller's legal authority, investigate mortgages and liens, and identify any restrictions affecting the property. A professional survey should establish that the land boundaries match the documents and those buildings, access routes, and shared facilities are correctly represented. Where the jurisdiction uses older deeds-based records, the title investigation may require additional historical checks.
For newly built or off-plan properties, investigate the developer's track record, financial position, construction permits, land ownership, building approvals, completion schedule, and contract terms. Confirm how deposits are protected, what happens if construction is delayed, and whether the buyer can recover money if key conditions are not met. Inspect existing buildings for structural defects, water damage, drainage problems, electrical safety, plumbing, and the condition of roofs and windows. If the property belongs to a condominium or resort, review its governing documents, service charges, reserve fund, rental restrictions, and any planned major assessments. Do not transfer the final purchase funds until the required legal checks and completion conditions have been satisfied. A carefully reviewed property may take longer to buy, but that delay can prevent expensive disputes later.
8. Understand Hurricane Exposure, Insurance, and Maintenance Costs
Climate and natural hazards must be part of the investment calculation, not an afterthought. Caribbean locations face different combinations of hurricane exposure, storm surge, coastal erosion, flooding, heavy rainfall, earthquakes, and, in some areas, volcanic hazards. A property close to the sea may command higher rental rates but also face greater exposure to salt corrosion, wind damage, and coastal flooding. Risk varies considerably between islands and even between neighbourhoods on the same island, so a regional average is not enough. Check the property's elevation, drainage, roof design, building materials, access roads, and history of storm or flood damage before purchasing.
Obtain an insurance quotation for the specific property during due diligence rather than estimating premiums from a nearby listing. Confirm what the policy covers, including windstorm, hurricane, flood, earthquake, contents, liability, and loss of rental income where available. Some policies have separate deductibles for named storms or other catastrophe events, and certain types of damage may be excluded. Also determine whether the building can be insured for its full rebuilding cost and whether a lender requires particular coverage. Annual maintenance should include roof inspections, corrosion control, pest prevention, air-conditioning servicing, plumbing checks, and preparation for the storm season. Properties in remote areas may require additional spending on water storage, backup power, security, and access improvements. A property that cannot obtain adequate insurance at a reasonable cost may be a poor investment even if the asking price appears attractive.
9. Plan for Property Management, Taxes, and Future Resale
Managing a Caribbean property from another country requires a reliable local system. Holiday rentals may need guest communication, cleaning, check-ins, emergency repairs, marketing, and regular inspections. Long-term rentals require tenant screening, rent collection, lease administration, and maintenance coordination. A professional property manager can handle these tasks, but the agreement should clearly state fees, authority to approve repairs, reporting frequency, and responsibility for handling complaints or emergencies. Request references from existing clients and review the manager's experience with properties similar to yours. If you plan to manage the property yourself, consider travel costs, time differences, and the difficulty of responding to urgent problems from abroad.
Tax planning must cover the country where the property is located as well as the country where you are tax-resident. Rental income may be taxable locally, and additional rules can apply to non-resident landlords or short-term accommodation businesses. Property taxes, withholding requirements, corporate reporting, and capital gains treatment differ by jurisdiction and can change over time. Before buying, obtain advice on how rental profits will be reported, whether any tax treaty or foreign-tax credit applies, and what documentation is needed to transfer profits or sale proceeds home. Also plan your exit strategy: identify likely future buyers, estimate selling costs, and consider whether foreign-purchaser licences or citizenship-programme conditions could affect resale. A property should not be judged solely by how much rent it might earn this year; its eventual resale value and the time needed to sell are equally important.
10. Follow a Step-by-Step Buying Strategy and Avoid Common Mistakes
A disciplined buying process helps foreign investors control legal, financial, and operational risks. Start by defining your budget, purpose, preferred property type, and minimum acceptable return. Shortlist two or three destinations and compare ownership rules, taxes, tourism demand, insurance costs, infrastructure, and access from your home country. Then select a property based on documented market evidence, appoint an independent local attorney, and arrange a professional survey and inspection. Obtain written estimates of transaction costs, annual expenses, and any required foreign ownership licence before making an unconditional commitment. For off-plan projects, investigate the developer carefully and have the contract reviewed before transferring funds.
Avoid buying only because an agent promises high rental returns, rapid appreciation, easy resale, or residency benefits. Do not assume that every beach property is a safe investment, that every resort will maintain high occupancy, or that every citizenship-by-investment property can be resold quickly. Keep emergency funds separate from the purchase budget, avoid sending money to unverified accounts, and use formal contracts with clear payment conditions. If citizenship or residency is a goal, verify the programme through the relevant government authority and account for application fees, holding periods, and eligibility conditions separately from the property's commercial value. Finally, seek local legal, tax, insurance, and financial advice before completion. A successful investment is one whose costs, legal position, risks, and exit options you understand before committing your money.
Conclusion
Caribbean real estate can offer opportunities for overseas buyers seeking rental income, a second home, commercial property, or long-term asset ownership. The right investment, however, depends on the specific country, property, purchase price, legal requirements, and ongoing operating costs. Foreign ownership rules, taxes, insurance availability, financing conditions, and rental demand must all be checked individually rather than assumed to be the same across the region. Buyers who verify title, calculate net returns, assess climate exposure, and plan for resale are better positioned to make informed decisions. The most practical approach is to treat Caribbean property as a long-term financial commitment, not simply a lifestyle purchase.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0